Friday, October 2, 2020
Tips For House Fire Insurance Claims
Watch on YouTube here: Tips For House Fire Insurance Claims
Via https://www.youtube.com/channel/UCcZImr64sN4bR4BB_JA82vg/videos

Thursday, September 24, 2020
Fire Insurance Claims: Tips & What to Expect for Fire Damage Insurance Claims
You buy homeowners insurance to protect against unexpected events – including house fires.
House fires are devastating. However, insurance protects you. Your home insurance policy should compensate you for the cost of repairing or replacing your home – and anything inside your home – after fire damage.
House fire insurance claims can be messy and expensive. Most homeowners have zero experience with fire insurance claims – and insurers may try to take advantage.
We’re covering the best fire insurance claim tips, examples and more.
How a Fire Insurance Claim Works
Fire can cause different types of damage to a property. Some fires totally destroy a property, leading to a total loss insurance claim. Others fire only damage one or two rooms or an outdoor area – but cause smoke or soot damage throughout the property.
Fire damage insurance claims come in different varieties, but insurance claims tend to proceed in a similar way. Below, we’ll list the typical progression of a fire insurance claim – from the first steps to the last.
- Secure the Scene: Put out the fire. Contact emergency services. Make sure every person and pet in your household is safe. Take steps to limit further damage. Place a tarp over the hole in your roof, for example, to prevent water from flowing in.
- Contact your Insurer and Start the Claim: All insurers have a 24/7 claims hotline. Contact your insurer to start the claim process. Your insurer will give your claim a number, then explain the next steps to take.
- Wait for the Adjuster: Typically, your insurer sends one of their adjusters to your property to inspect and verify the damage. The adjuster may tell you to hire an emergency restoration contractor to further secure the scene and begin repairing damage.
- Accept Emergency Funds: At this point, your adjuster may wire emergency funds to your bank account. These funds can cover accommodations (if you’re unable to live in your home), meals, and similar expenses. These funds will be deducted from any final settlement.
- Get Multiple Estimates: Your insurance company may provide an estimate on how much repairs should cost. This estimate may be ideal – or it may be too low based on the prices charged by local contractors. Get multiple estimates for repairing or restoring your property.
- Restore or Repair Damage: For severe fire damage insurance claims, emergency restoration contractors may arrive on scene immediately to begin repairing damage. Restoration contactors will repair or restore your property to its pre-loss condition. The contractors will also identify items that can be salvaged – and items that need to be thrown away.
- Keep All Receipts: Throughout this process, it’s crucial to document everything. Keep all receipts for hotel accommodations, meals, and other expenses. Anything you pay while living away from your home should be covered by insurance (within reason). You buy insurance to cover these expenses.
- Document Everything: You should also document everything throughout this process. In addition to keeping receipts, keep photos or videos of all damaged items, all property damage, and other things affected by the fire.
- Inspect your Entire Property for Damage: Fire damage insurance claims can get messy. It may seem like a minor fire only in one corner of your home – but soot and smoke damage can spread throughout your property to affect multiple rooms of your home. Carefully inspect your property or hire experts who can inspect your property. Your HVAC system may be filled with smoke and soot, for example, that will spread throughout your home if not cleaned.
- Consider Hiring a Public Adjuster: If you encounter issues at any of the steps above, then consider hiring a public adjuster. A public adjuster works on your behalf to maximize fire damage insurance claim compensation. Some people hire a public adjuster immediately after a loss to ensure a smooth claim process. Others hire a public adjuster after a claim is denied – or after the insurer offers a low payout. A good public adjuster specializing in fire damage claims can easily be worth the small fee, and some property owners double or even triple their payout.
[big_contactus]
Fire Insurance Claims Examples
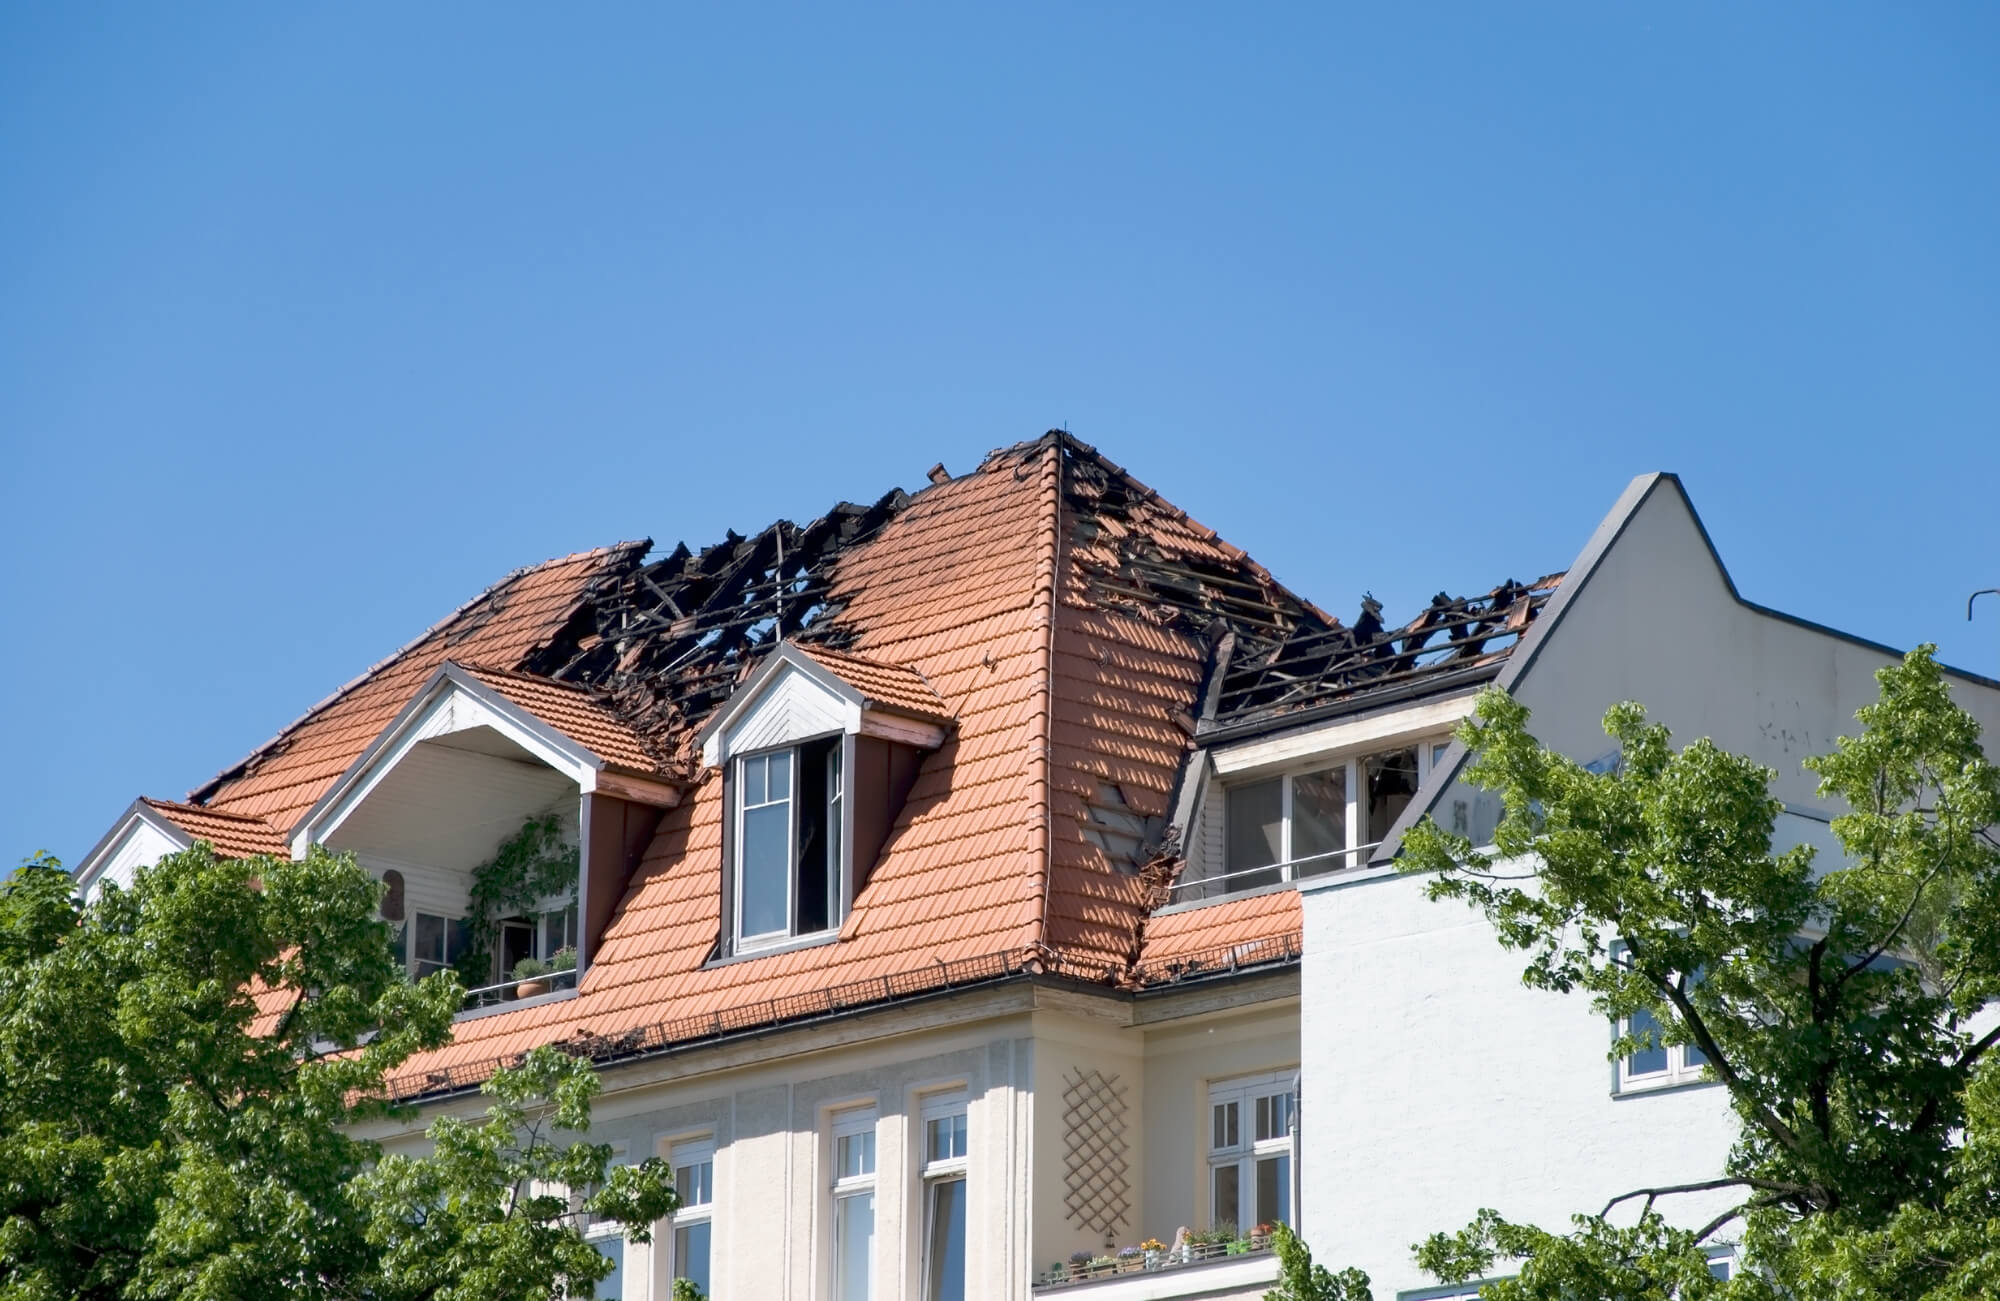 Some fire damage insurance claims are million-dollar claims with total loss of property. Other claims are relatively minor, causing a few thousand dollars of smoke and soot damage.
Below, we’ve highlighted some examples of fire damage insurance claims, including fire damage claims at homes and commercial fire damage claims for businesses.
Historic House in Dallas
A historic home in Dallas was insured for $421,000 and destroyed by a large fire. It was a total loss, although the homeowner and insurance company disagreed on the amount required to pay. Although the home was insured for $421,000, the insurer valued the property at $365,000. According to the insurer, they only had to pay $365,000 to cover the actual cash value of the property – the exact value of the property at the time the loss occurred. The homeowner hired a public adjuster. The public adjuster identified features and fixtures in the home that increased the value significantly. Ultimately, the insurer paid the full $421,000 value of the policy, including additional coverage for debris removal, damaged landscaping, and other expenses.
Lumber Company in Tennessee
A lumber company in Tennessee experienced a fire that led to the loss of $5 million of inventory. The insurer delayed and denied the claim at first, demanding evidence of the $5 million of lost inventory. After hiring a public adjuster, the lumber company was able to receive the full amount owed for the loss of inventory. The public adjuster also argued for the coverage of moving expenses, as the lumber company needed to adjust operations during the fire damage restoration process. Overall, the company significantly improved its payout by hiring a public adjuster.
House Fire in the Suburbs of San Antonio
A homeowner in suburban San Antonio received a call at work that her house was on fire. An electrical surge had sparked a fire within the kitchen. A neighbor spotted the fire and alerted emergency services quickly, and firefighters stopped damage from spreading to other parts of the home. The insurance company’s adjuster initially offered a payout of $34,000 to cover the cost of repairing and restoring damage in the kitchen. The homeowner disagreed with that valuation, however, and hired a public adjuster to get added compensation. The public adjuster identified smoke and soot damage throughout the property, ultimately arguing for additional coverage. The overall, final cost of the fire damage insurance claim was close to $70,000, and the homeowner received this amount with help from a public adjuster.
[dynamic_contact_us text="Contact A Public Adjuster"]
How to Deal with an Insurance Adjuster After a House Fire: The Best Tips & Strategies
Your insurance company’s adjuster is a salaried employee of your insurance company. That adjuster’s goal is to minimize payout – not provide you with as much money as you like.
Remember: insurance companies are for-profit businesses. They want to make as much money as possible while paying as little for your claim as they’re legally obligated to pay.
Unfortunately, most homeowners have zero fire damage insurance claim experience. Your insurance company’s adjuster may take advantage of this naivety to offer low payouts or deny your claim based on hidden contract terms.
We want to help. You can hire a public adjuster to ensure complete coverage for your fire damage insurance claim. See tips for dealing with insurance adjusters along with the tips below for dealing with fire insurance claims:
Document All Additional Costs from the Fire: Your homeowners insurance policy covers additional living expenses (labeled as ‘ALE’ on most policies). If a house fire destroys your home and forces you to move out, then you may need to pay ALE in the form of hotels, meals, a rental car, cleaning supplies, and other expenses. Track all of these costs and keep receipts. Your insurer is obligated to cover most costs incurred as a result of your house fire.
Take Photos and Videos: Many homeowners are surprised by how much evidence insurers request after a house fire. The more photos and videos you have of damage, the better. Take photos and videos of damaged property, damaged items, and anything else. Make sure you take these photos before cleanups or repairs start. Otherwise, it may be too late.
Create a Home Inventory Today: Most homeowners don’t keep an inventory of everything in the home – but you should. Proactive homeowners keep an inventory of everything in the house, and they update this inventory regularly. If a house fire occurs, you have specific information about what was damaged and what your insurer needs to cover.
Review Your Policy Regularly: By reviewing your homeowners insurance policy regularly, you can avoid being underinsured.
How Commercial Fire Damage Claims Work
Commercial fire damage insurance claims work in a similar way. Every year, businesses across the United States suffer $3 billion in commercial and industrial property damage due to fire.
One of the major differences between a residential and commercial fire damage claim is with the value of the claim. Businesses could lose millions in a fire, which means a more complicated insurance claim process.
Fortunately, public adjusters can help with commercial fire damage claims as well. Many public adjusters specialize in fire damage insurance claims for businesses, fighting on behalf of business owners to secure maximum compensation.
Total Loss Fire Claims
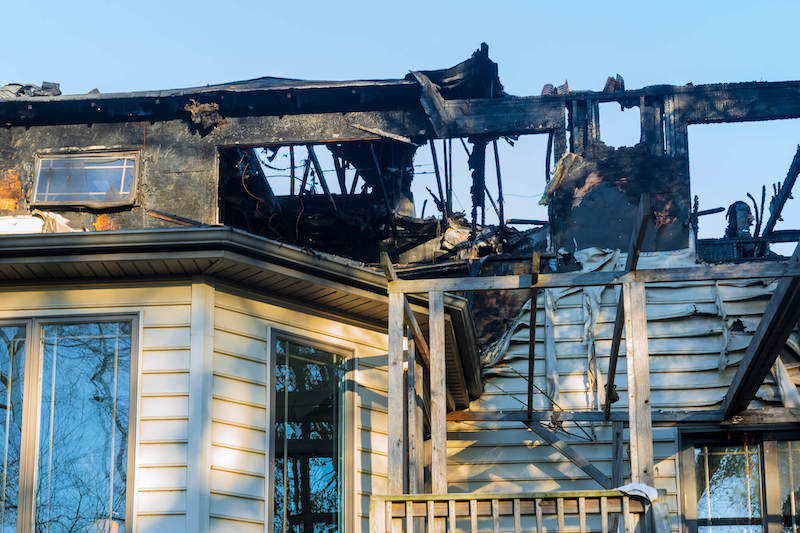 With a total loss fire claim, the cost of fire damage exceeds your policy’s value. You might have lost $500,000 worth of property and possessions in a devastating house fire, for example, but you only have $300,000 of insurance coverage.
In a total loss fire damage insurance claim, your insurer pays up to the limits of your policy. You cover remaining costs out of pocket.
Many homeowners who experience a total loss are underinsured, which means you have too little insurance to cover your property and possessions.
Review your insurance policy, property value, and possession value regularly to ensure they line up. Otherwise, you could be left dangerously underinsured after a house fire.
How a Public Adjuster Helps with a Fire Insurance Claim
Many people hire a public adjuster to help with a fire damage insurance claim. When you hire a public adjuster, you’re getting a genuine insurance expert to support your claim, maximize compensation, and ensure a smooth settlement process.
Perks of hiring a public adjuster include:
- Obtain a fair claim settlement payout much higher than the initial offer
- Get expert assistance at every step of the fire damage insurance claim process
- Let a specialist negotiate with the insurer on your behalf for the highest possible compensation
- Complete management of the fire damage insurance claim, repairs, and restorations from beginning to end
- Get a second opinion from an expert on home valuation, policy coverage, and repair costs
- Get an insurance specialist who represents your best interests – not your insurer’s best interests
[big_contactus]
Most public adjusters only charge a fee after you accept the final payout from your insurer, at which point they take a pre-arranged cut of the payout. Public adjusters charge between 5% and 25% fees, based on their experience, the size of the claim, and other factors.
After hiring a public adjuster, many of our customers agree: it feels like a weight has been lifted off your back, and you can relax knowing an expert is supporting your claim at very step.
Final Word On Fire Insurance Claims
House fire insurance claims are tricky. Fortunately, with preparation and expert assistance, you can maximize compensation.
After a house fire, your insurance company needs to compensate you for the cost of repairing or replacing any damage, including damage to your property and possessions. If your insurance company fails to live up to this agreement, then your insurer may be acting in bad faith.
For expert assistance with your fire damage insurance claim, contact ClaimsMate today for a free consultation.
Our public adjusters have decades of proven experience maximizing compensation with fire insurance claims.
Article Source Here: Fire Insurance Claims: Tips & What to Expect for Fire Damage Insurance Claims
Monday, August 24, 2020
How Do Insurance Companies Pay Out Claims? How Are Homeowners Insurance Claims Paid?
Many homeowners are unfamiliar with the home insurance claim process – and that’s okay. Some homeowners never file a claim.
Insurance companies pay claims in different ways. Depending on the type of claim, the amount owed, the work required, and other factors, insurance companies pay claims differently.
Some insurers directly pay a contractor, for example, and that contractor performs the required work on your home. Other insurers send you a check for the owed amount, and you can spend that check however you like.
Today, we’re explaining how insurance companies pay out claims, including how homeowners insurance claims are paid.
How a Homeowners Insurance Claim Works
No two homeowners insurance claims are alike. However, most homeowners insurance claims follow a similar claim process:
- You File the Claim: You contact your insurance company to notify them of the loss. The insurance company starts your claim and gives you a claim number.
- Your Insurer Evaluates the Claim: The insurer evaluates your claim. The insurer will verify any documentation you provided. The insurer dispatches an adjuster to evaluate the damage. If you have a complex claim, then it could take weeks to evaluate damages. For simpler claims, the insurer could check your paperwork and pay the claim immediately.
- Your Insurer Approves or Denies the Claim: Based on their evaluation, the insurer will either approve or deny your claim. If the insurer approves your claim, you will receive payout (or move forward with repairs). If the insurer denies your claim, then you might need to send additional evidence, hire a public adjuster, or hire an insurance attorney. If your claim is denied, see Reason Insurance Claims Are Denied and How To Dispute Claim Denials.
- You Receive your Payment: Finally, if the insurer approves your claim and there are no other issues, then you will receive your payment.
How An Insurance Company Pays You
If your homeowners insurance claim is approved, then the insurance company will pay your claim. The insurance company agrees to cover your damages, and you will receive compensation for those damages.
Depending on the type of claim and the extent of damages, an insurance company could pay you in different ways.
The two most common ways to receive payment for a homeowners include claim include:
- By check
- By paying vendors or contractors on your behalf
How Much Money Will You Receive For Your Claim?
The amount of money you receive for your insurance claim is based on two factors:
- The amount of coverage you have
- The value of the covered damage
If your home suffered $150,000 of damage during a hurricane, for example, but you only have $100,000 of homeowners insurance coverage, then your insurance will pay you up to the limits of your policy, then you cover the remaining amount out of pocket. In this case, you receive a payment from your insurance company for $100,000, and then you cover the remaining $50,000 out of pocket.
You Could Receive Multiple Payments
For larger insurance claims, you could receive multiple payments. Instead of receiving a single check for $100,000, for example, you might receive an initial check for $20,000 and then a final check for $80,000.
Insurers could send an initial check to cover emergency expenses. If your house burns down, for example, then you might be forced to live in a hotel for the near future. You might need to pay emergency contractors to repair the damage and secure the scene. Your insurer sends you an initial payment to cover these expenses.
Then, once the insurance claim is complete, the insurer sends a second or third check to cover any remaining costs. If the insurer assesses the total damage to be worth $100,000, for example, then you receive a final check for $80,000 (in addition to the initial check of $20,000).
You Might Not Have Full Control Over Payment
Many homeowners are surprised to discover they don’t have full control over payment. A lender or management company might control your payment.
If you have a mortgage on your home, for example, then the check for home repairs will be made out to you and the mortgage lender (like your bank). Most lenders require this on your homeowners insurance policy. As part of your lending agreement, you are required to name your insurer on any homeowners insurance policy, which means they are a party to any insurance payments made under that policy.
Or, if you live in a condo or apartment complex, your management company might need to be named on the policy. Your building’s management company (or the building’s owner) must be named as a co-insured.
Why does the lender or owner need to be named on the policy? The lender needs to ensure the necessary repairs are made. You do not completely own your home: your lender partly owns your home, and your home is the collateral that secures the loan.
In these cases, you cannot make a $100,000 insurance claim, then simply pocket the money and avoid repairing the property. You must use the insurance money to repair the property.
If an owner or financial company is named as a co-insured, then that entity needs to endorse the claims payment check before you cash or deposit it.
Depending on the situation, lenders could also put the insurance money into an escrow account. This escrow account pays for repairs as the work is completed.
In co-insured situations, the mortgage lender may need to know about certain repairs. Your mortgage lender may need to see the contractor’s bid, for example, and determine how much the contractor wants upfront to start the job. Then, the lender may want to inspect the finished job after the work is complete. If the work is satisfactory, the lender releases the funds to the contractor.
Total Loss Insurance Claim Payouts
After a serious incident, your home might be a total loss. The covered event may have caused more damage to your home than your home is worth. In this case, your home is declared a total loss. You can read tips about dealing with total loss insurance claims in this article.
If your home has extensive fire or water damage, for example, then it could be a total loss. Your home may need to be demolished.
In this situation, your insurer works through the same step-by-step payment process mentioned above. However, there are slight differences with a total loss claim.
With a total loss claim, you can decide how to spend your insurance payout. You might use a portion of the payout to pay the balance of your mortgage, for example. You could use remaining funds to rebuild your home, buy a different lot, or move to a different neighborhood entirely.
In some cases, state law dictates how a total loss insurance claim works. State law may stipulate who gets paid and how you spend your total loss insurance payout.
With most total loss insurance claims, the entire house and its contents are damaged beyond repair. In this situation, your insurer might pay to the limits of your policy, giving you a check for the full value of your policy.
When Insurance Pays a Contractor Directly
In some cases, insurers send you a check for the covered amount. In other cases, insurers work directly with a contractor. The insurance company sends money to the contractor, the contractor completes repairs on your home, and your insurance claim is closed.
Some contractors may ask you to sign a ‘direction to pay’ form. This form allows the insurance company to pay the contractor directly.
With a direction to pay form, you authorize the contractor to manage your insurance payout. This form is a legal document. You need to read it carefully to ensure you understand everything it means.
Some shady contractors are caught with malicious direction to pay forms. These forms authorize the contractor to handle the entire claim, for example. Other contractors obtain a direction to pay form, then disappear with your insurance money without performing repairs (or after performing low-quality repairs). Find more tips on what to look out for with insurance claim contractor scams.
All ALE Checks Are Sent Directly to You
Your homeowners insurance should cover additional living expenses (ALE). If you are forced out of your home due to a covered incident, then you might have additional living expenses – like hotels, meals, and rental cars.
Your insurance company sends ALE checks directly to you. These payments have nothing to do with home repairs, and they will not be sent to your contractor or a lender.
You Receive Payment for Possessions Based on Cash Value
Your home is filled with your possessions. Your homeowners insurance covers most of these possessions.
If your TV is worth $2,000, for example, and your laptop is worth $1,500, then your homeowners insurance will pay you $3,500 to compensate for the loss of these items.
Your insurance covers items based on their cash value. You might have paid $1,500 for your laptop two years ago, although that laptop is only worth $800 today. This is the cash value of your laptop: it’s the cost of the item minus depreciation.
To claim your damaged belongings, you need to submit a list of items to your insurance company. Some experts recommend keeping a home inventory to make this process easier.
Even if you have a replacement cost policy (which is more expensive), your insurer covers the cash value of items first. Your insurer verifies the value of each item, then subtracts depreciation.
If You Want Replacement Value for Possessions, You Must Replace Them
Your insurance company could fully reimburse you for damaged items. However, to receive the full replacement value for your items, you need to actually replace those items.
If you lost your $1,500 laptop in a house fire, for example, then you might replace that item with a $1,500 laptop purchased brand new. Your insurer requires proof that you replaced the item (like a receipt). Then, the insurer pays the difference between the cash value you initially received for the lost item and the full cost of the replacement item.
You receive payment based on the value of the replaced item – not the value of buying a newer item. Your laptop cost $1,500 two years ago, but it does not cost $1,500 today. You can buy the same laptop brand new for $1,000 today. Your insurance company compensates you for that value – not the value of buying a better item.
Most insurers give you several months to purchase replacement items. Ask your insurance agent about any timeframe requirements.
Claim Payment Problems? What Happens Next
In a perfect world, your insurance company accepts your claim, sends payment, and closes your claim.
Unfortunately, insurance claims don’t always work that way. Insurance claims can get messy. Insurers can deny your claim or reduce your payout.
Sometimes, insurers need more evidence. You might need to submit more receipts, photographs, and other documentation.
In other cases, insurers are acting maliciously. They demand too much evidence. They deny your claim without sufficient reason. They drag their feet, take too long to contact you, and operate in bad faith.
When insurers operate in bad faith with homeowners insurance payouts, consider hiring a public adjuster or insurance attorney.
These professionals represent you against your insurance company. They tell your insurer you are taking the claim seriously. They fight to ensure you get every penny legally owed to you.
Schedule a free consultation with a public adjuster today. Discover your options for maximizing homeowners insurance payouts.
Original Post Here: How Do Insurance Companies Pay Out Claims? How Are Homeowners Insurance Claims Paid?
Thursday, August 20, 2020
Insurance Claim Inspections for Property Damage
Property damage insurance claims can become quite complicated. The insurance company will typically require an inspection of the damaged property.
Most homeowners and business owners are unfamiliar with property damage insurance claims. You might have never filed a claim in your life. Even if you have dealt with insurance before, property damage insurance claims can vary widely.
How do insurance claim inspections work? What should you expect during your property damage claim inspection? How should you prepare for an inspection? Let’s find out.
How a Property Damage Insurance Claim Works
Property damage insurance claims come in all different types and sizes.
However, they generally proceed in a similar way:
- You File the Claim: You experience a loss, then file a claim with your insurer. You contact your insurance company, and an insurance agent handles your claim, then assigns a claims number.
- The Insurer Evaluates the Claim: Next, the insurer evaluates the claim. The insurer sends an adjuster to your property to inspect the damage. For a smaller and simpler claim, the insurer might approve the claim with photos or videos of the damage.
- Your Insurer Approves or Denies the Claim: Your insurer approves or denies your insurance claim. The insurer might send you a check to compensate you for the property damage. Or, the insurer might directly pay a local contractor to complete the repairs.
- You Close Your Claim: After the repairs are complete, and you receive payment for your insurance claim, your claim is closed. Your insurer has fulfilled its obligation to make you whole again after the incident.
How Property Damage Insurance Claim Inspections Work
Property damage insurance claim inspections occur at ‘Step 2’. The insurer evaluates your claim, then approves or denies your claim based on the inspection.
For smaller claims, the insurer might not require an inspection. If the claim is worth less than $1,000, for example, or occurred during a simple event (like a routine storm that affected multiple homes in the area), then the insurer might approve your claim with photos, videos, and other evidence of the documented area. An adjuster may not need to physically inspect your property damage.
In most cases, however, the insurer will inspect the property damage before approving or denying your claim.
The insurer will dispatch an adjuster to your property to evaluate the claim. The adjuster’s goal is to analyze the property damage, then pay you the amount legally required for your insurance claim, based on your insurance policy.
Remember: insurance companies are for-profit businesses. Their goal is to make money: not pay out more money than they need to pay. They will pay out the minimum amount they are required to pay based on the terms of the insurance contract – nothing more.
Your insurance company’s adjuster will inspect the damage to verify the damage is legitimate. The adjuster might check for signs of wear and tear, fraud or deliberate damage, for example. The insurer might check for other damage around the property.
Based on the damage and the limits of your homeowners policy, the adjuster will decide on your property damage insurance payout.
What to Expect During an Inspection
There are three types of inspections for property damage insurance claims:
- Contractor Inspections
- Insurance Adjuster Inspections
- Public Adjuster Inspections
Contractor Inspections For Insurance Claims
You might schedule an inspection with a local contractor to determine how much it costs to repair the damage. Many contractors provide free, no-obligations damage estimates. You can check how much it would cost to repair your damaged roof, for example, then decide whether it’s worth it to file a claim.
A good contractor will inspect your property, check the damage, then provide an itemized list and price estimate for repairing the damage. You can approach your insurance company with this estimate and make an insurance claim. Or, if you’d rather work outside of insurance, you can pay the contractor to make repairs directly.
Sometimes, damage is less severe than you anticipated. It might only cost $1,000 to repair the damage, for example. In these cases, it is often not worth it to file an insurance claim because your deductible may be higher than the repair cost.
You might request a contractor inspection before contacting your insurance company. Or, you might request a contractor inspection after. If you disagree with your insurance adjuster’s assessment, for example, then you might request a second opinion from a local contractor.
Insurance Adjuster Inspections For Insurance Claims
If you decide to file a claim, then your insurance company will send an adjuster to your property. Your insurance company’s adjuster is either a salaried employee or independent contract adjuster of the insurance company. The adjuster will inspect the property damage to ensure it’s covered by your homeowners insurance policy.
Some adjusters will estimate the cost of repairing the damage. Other adjusters will ask a contractor to make an estimate. Adjusters may not be qualified to estimate construction or repair costs. However, all adjusters are professionally trained to assess damage.
Public Adjuster Inspections For Insurance Claims
A Public Insurance Adjuster is quite similar to an insurance company adjuster when it comes to experience and duties performed - with one major difference. A Public Adjuster is hired by the insured/policyholder and works to represent their best interests instead of the insurance company. Many Public Adjusters formerly worked as insurance adjusters for insurance companies, before going out on their own to represent policyholders. Public Adjusters have additional experience with analyzing insurance policies and inspecting property damage from a goal and perspective of truly obtaining a fair and adequate claim settlement, so policyholders can fully restore or repair damaged property. When using a Public Adjuster for a property damage claim, it is advantageous to have the Public Adjuster present at the first inspection with the insurance company’s adjuster. This can reduce the likelihood of disagreements, things being overlooked, and the need for scheduling a second inspection.
[big_contactus]
What Happens During a Property Damage Inspection?
Your insurance company’s adjuster might visit your property one or more times to inspect the damage. An adjuster might inspect the initial damage after the loss, for example, and then revisit your home after repairs are complete to assess repairs.
Things to expect during a property damage inspection include:
Full Inspection of Damaged Property & Items: The adjuster will inspect any property damage in and around your home. The adjuster will verify the damage is legitimate. If you’re making a claim for hail damage to your roof, for example, then the adjuster will inspect the damage to ensure it occurred during the latest hailstorm and not years ago.
Damaged or Destroyed Items: Your adjuster may ask for a list or inventory of damaged items. Give your adjuster this list along with any receipts. Do not throw out damaged items until the adjuster has visited. You may need to take photographs of any items you intend to claim. Consider photographing or videotaping all property damage – including physical damage to your property and any possessions. The more evidence you have, the smoother your claim will be.
Structural Damage: The adjuster will check structural damage on and around your property. The adjuster will look for structural damage to your home, pool, garage, shed, and any other buildings.
Signs of Fraud of Intentional Damage: You cannot burn down your own property and make an insurance claim. During the inspection, the adjuster will look for signs of insurance fraud – like intentional damage or old damage from a previous incident.
For more tips on dealing with an insurance adjuster read the article here.
Other Things to Know About Insurance Claim Inspections for Property Damage
Insurance claim inspections for property damage can be complicated. Other things to know about inspections include:
Make Temporary Repairs & Control the Scene: We covered that it is best to avoid removing damaged items until the inspection. That’s true. However, you must still make temporary repairs and secure the scene. If your home is flooding from a burst pipe, for example, then you shouldn’t simply shrug your shoulders and watch water fill the house. You need to secure the scene, turn off the water, and make temporary repairs (if safe to do so). Most insurers tell you to contact an emergency restoration company immediately.
Track Additional Living Expenses: If forced from your home due to property damage, track your additional living expenses. Your homeowners insurance covers additional living expenses (ALE) incurred if you are unable to remain in your home. That means meals, accommodations, and other costs are covered. Keep receipts from any hotels, restaurants, rental car companies, and more.
Consider Replacement Cost and Actual Cash Value: Homeowners insurance policies cover possessions in two different ways. Some cover the actual cash value of your items, which is the value of the item minus its depreciation. Higher-end homeowners insurance policies cover replacement value, which is the amount needed to replace the item without depreciation.
Remember Policy Limits: Your homeowners insurance policy has specific policy limits. If your home was worth $400,000, for example, and burned down in a fire, but you only have a $200,000 home insurance policy, then you will receive $200,000 from your insurance company. Your insurance company won’t pay more than the value of your policy.
Coverage for Improvements: Many homeowners are surprised to find insurance has reduced their claim because they made significant improvements to the house. You might have added a deck or renovated your bathroom, for example, without informing your insurer of the changes. If your insurer isn’t aware of the changes, then you will not receive compensation.
Conclusion: Contact a Public Adjuster or Contractor for a Second Opinion
During an inspection, an insurance adjuster is doing his or her job. Many insurance adjusters are reputable, honest people. They inspect the damage, assess your claim, and provide a report.
However, your adjuster is also an employee of your insurance company, and adjusters want to keep their employers happy. The adjuster’s focus may be to cover the bare minimum amount legally required – nothing more.
If you are unhappy with an insurance company’s inspection for property damage, talk to an experienced Public Adjuster for a second opinion.
See Full Article Here: Insurance Claim Inspections for Property Damage
Wednesday, August 12, 2020
Filing an Insurance Claim: How to File a Claim For Property Damage
Most home and business owners aren’t experts with property insurance claims.
How could you possibly be an expert if you’ve never filed a claim? Many property owners go their entire lives without making a significant insurance claim!
We’re explaining how to file a property damage insurance claim, including the steps to take, tips for maximizing your claim, and how to ensure your claim gets approved with the best chance for a fair settlement.
How to File a Homeowners Insurance Claim
A standard insurance claim for property damage goes through an eight-step process:
- Notify your insurance company
- Meet with the insurance company’s adjuster
- Protect your property and possessions
- Secure temporary accommodations (if necessary)
- Submit an inventory of damaged or destroyed items
- Estimate the total repair and replacement cost
- Repair or replace everything to pre-loss condition
- Move back into your home
We’ll cover the basics of these 8 steps below. For additional information and resources, also see The Claim Process: Guide To How Insurance Claims Work.
Step 1) Notify your insurance company
Start by notifying your insurance company. After noticing a loss, you need to take action to protect your property. Contact your insurance company’s 24/7 claims hotline to begin the claims process.
Even if you don’t file a claim, you may still decide to contact your insurance company. Your insurer can help you decide if filing a claim is worth it. Your insurer can also explain the next steps to take.
Look up your insurance company’s 24/7 claims hotline and speak with a representative. Your insurer can dispatch an adjuster to your house, recommend a 24/7 emergency contractor, and explain how to take the next steps.
Step 2) Meet with the insurance company’s adjuster
The insurance company will send an adjuster to your property to inspect the damages. This adjuster is your representative at the insurance company. This is the person you will be interacting with throughout your claim. Also see valuable tips for dealing with the home insurance adjuster.
Your insurance company’s adjuster is either a salaried employee or independent adjuster working for your insurance company. The adjuster will analyze the damage, assess your policy, and determine what is and isn’t covered. The adjuster will interact with the homeowner and contractors throughout the restoration process.
Step 3) Protect your property and possessions
Depending on the severity of the incident, the insurance company or adjuster may recommend hiring a 24/7 emergency contractor or restoration company immediately. A contractor can arrive any time of day or night to secure the scene. The contractor can setup fans and drying equipment to manage water damage, for example, or haul away fire-damaged materials after a house fire.
Your insurance policy requires you to secure the scene after an incident. If you do not take steps to limit damage to your property, then your insurer could deny part or all of the claim because of a ‘failure to mitigate’. You cannot allow extra damage to occur to your home after an accident. You must take reasonable precautions to prevent further damage – like placing a tarp over the hole in your roof, shutting off water, or setting up fans if safe to do so.
Your insurance company’s adjuster will explain the next steps to take after a disaster or accident. The adjuster might send money to your account immediately. This money can cover your emergency expenses – like the cost of a hotel and the initial cost of the emergency contractor.
Step 4) Secure temporary accommodations (if necessary)
After a serious incident, your home might be unlivable. You may need to move out of your property during repairs.
If you have to move into a hotel, then home insurance should cover your accommodation expenses. Homeowners insurance covers the cost of repairing your property and possessions. It also covers additional living expenses (ALE) if you cannot remain in your home.
After moving out of your home, track all receipts. Your homeowners insurance could cover the cost of a hotel, dining out, renting a car, and any other expenses incurred because of your loss.
Most insurance policies cover your expenses up to a certain limit per day. You might receive compensation up to $125 per night for a hotel, for example, and $75 per day for food.
Step 5) Submit an inventory of damaged or destroyed items
To receive compensation for your damaged or destroyed items, you need to create an inventory. That inventory lists the items that were damaged along with their approximate value.
Some homeowners are extra cautious. They create an inventory of their home’s contents every 6 to 12 months. These homeowners take photographs of every valuable item, keep receipts of everything they ever purchased, and track it all in a spreadsheet. Read about the importance of regularly documenting and taking inventory.
Most homeowners do not have an up-to-date complete home inventory, and that’s okay. Gather your damaged items. Take photographs of the damaged items and estimate the value of each item. You will need to submit all of this information to your insurance company to receive compensation. As part of the process of any property damage insurance claim, the insured needs to complete detailed proof of loss forms.
Insurers provide compensation for items in two ways: actual cash value or replacement value:
Actual Cash Value: With actual cash value, the insurer analyzes the value of your items, then subtracts depreciation. If you bought a $2,000 laptop three years ago, then that laptop may be worth only $500 today with depreciation.
Replacement Value: With replacement value, your insurer compensates you for the cost of replacing your damaged items – not just the value you lost when the item was destroyed. If it costs $1,000 to buy a comparable laptop today, then the insurer gives you $1,000 to replace your laptop. You must actually replace the item to receive compensation. Your insurer will require a receipt, then give compensation based on the replacement value of your item.
Step 6) Estimate the total repair and replacement cost
The next step is to calculate the cost of repairing and replacing your home and its contents. To do this, your insurer will typically recommend contractors in your area. This contractor will analyze the damage, then determine the approximate cost to repair your damages.
For significant repairs, it’s a good idea to get multiple quotes. Calculating the cost of extensive repairs can be difficult. If a contractor makes a mistake during the estimate (say, by under-estimating cost), it could lower your final payout.
Request a quote from reputable local contractors. If you disagree with your insurer’s assessment of damages, then consider contacting a public insurance adjuster or a third party contractor for an estimate. An experienced public adjuster or reputable third-party contractor can give you a better idea of how much everything costs.
To get help from a licensed insurance claim expert that fights for your best interests, talk to an experienced Public Adjuster.
[dynamic_contact_us text="Schedule a Free Consultation"]
Note About Total Loss Claims: If your home has significant damage, then it could be declared a total loss. A home that burns down, for example, could be a total loss. With a total loss, you have maxed out your insurance policy. The cost of repairing or replacing your property is more than your policy is worth. Your insurer pays to the limits of your policy, while you cover any remaining costs out of pocket. If you have a $100,000 policy, for example, and a fire caused $150,000 of damage to your property, then your insurer will pay $100,000, while you pay the remaining $50,000 out of pocket. Find more in depth information here about total loss property damage claims.
Step 7) Repair or replace everything to pre-loss condition
Once you have approved a contractor’s estimate, repairs can begin. Repair or replace everything to pre-loss condition. Depending on the damages, this step can take a few days – or a few months.
If you are forced to live outside of your home, be sure to track expenses. Keep receipts for all accommodations and meals. Track any additional costs you incur as a result of your home repairs. Many are surprised by how quickly costs can add up. By tracking everything, you can ensure you receive fair compensation from your insurance company.
Step 8) Move back into your home
After repairs are complete, you’re ready to move back into your home. Your home is safe and ready to be lived in once again.
What Happens If Something Goes Wrong with My Claim?
Not all insurance claims go as smoothly as outlined above. Your insurer could deny your claim or reduce payout. A contractor might go beyond your budget, forcing you to pay money out of pocket.
If something goes wrong with your claim, you have multiple options.
Talk to your Insurer: Sometimes, just talking to your insurer will solve your problem. Ask to speak with your adjuster’s supervisor, for example. Or, contact your insurer’s complaints hotline. Escalating the situation could help resolve your issue – or it could do nothing.
Hire a Public Adjuster: For higher-value insurance claims (over $10,000), it’s generally worth it to hire a public adjuster. A public adjuster works for you, analyzing your claim and negotiating with the insurance company on your behalf. Proven public adjusters often help obtain settlements that are 3 to 4 times higher than the one initially offered by the insurance company.
Speak with an Attorney: Public adjusters aren’t available in all states. In some states, attorneys specialize in insurance disputes and play a similar role to public adjusters. Attorneys can help you navigate the claims process and fight for the compensation legally owed to you. s
Schedule a free consultation with a public adjuster today. Educate yourself on your rights – and prevent an insurer from taking advantage of you.
Read Full Article Here: Filing an Insurance Claim: How to File a Claim For Property Damage
Subscribe to:
Posts (Atom)